For a long time, the commercial real estate negotiation seemed fairly straightforward.
A seller established a price.
A buyer negotiated that price.
A lender financed a portion of the acquisition.
The buyer brought the equity.
The transaction closed.
That framework still exists.
But increasingly, it is no longer the whole story.
Commercial real estate financing has become more complicated, more selective, and in many cases more creative. Interest rates are only one part of the equation. Lenders are paying closer attention to leverage, liquidity, debt coverage, asset quality, borrower strength, and what the buyer will still have available after the transaction closes.
As a result, buyers and sellers are beginning to negotiate something that received far less attention during the easy-money years:
Not just what the property will sell for, but how the deal will actually be funded.
That shift may become one of the defining characteristics of the next commercial real estate cycle.
The Cost of Money Is Only the Beginning
Interest rates naturally get most of the attention.
They are visible. They affect monthly debt service. They influence returns. And when rates move, investors immediately feel the difference.
But the current financing environment goes deeper than the interest rate printed on the loan documents.
The more consequential change may be the amount of risk lenders are willing to carry.
For some transactions, buyers who once expected traditional leverage are discovering that substantially more equity may be required to get a deal approved. In certain cases, that can mean bringing 40%, 50%, or even more of the purchase price to closing.
And the scrutiny does not necessarily stop once the down payment has been established.
Lenders are increasingly interested in the financial condition of the borrower after closing.
It is no longer enough to demonstrate that you can purchase the property.
The lender may also want confidence that you can continue to support it.
That changes the mathematics of the acquisition.
It changes the buyer pool.
And eventually, it changes the negotiation between buyer and seller.
A Good Deal Can Still Have a Financing Problem
This is an important distinction.
A property can make sense economically and still struggle to fit conventional lending parameters.
The location may be strong.
The income may be stable.
The buyer may understand the asset and believe in its future.
The seller may be motivated.
Yet the transaction can stall because the financing structure no longer works the way the parties initially expected.
That does not necessarily mean there is something wrong with the real estate.
It may mean the capital structure needs to change.
This is where commercial real estate becomes less about simply matching buyers with properties and more about structuring transactions.
The question shifts from:
“Does the buyer want the property?”
to:
“Is there a structure that allows both sides to accomplish what they need?”
Those are two very different conversations.
Seller Financing Is Reentering the Conversation
Seller financing is certainly not new.
What is changing is how often it is becoming part of the conversation.
When traditional lending cannot provide enough leverage — or when the cost, timing, or requirements of bank financing create obstacles — a seller may have an opportunity to become part of the capital stack.
That does not mean every seller should finance a buyer.
It does not mean seller financing is appropriate for every property.
But it does mean the structure deserves consideration in situations where the underlying deal is otherwise sound.
For the buyer, seller financing may reduce dependence on conventional debt or bridge a gap between available financing and the equity required to close.
For the seller, it may create an income stream, expand the available buyer pool, support the desired purchase price, or potentially provide tax-planning advantages depending on how the transaction is structured.
Those benefits come with risk and should always be reviewed with the appropriate legal, tax, and financial advisors.
But the larger point is difficult to ignore.
Sometimes the seller's best negotiation may not be giving up price.
It may be giving terms.
There is a significant difference between reducing a property's value by several hundred thousand dollars and agreeing to carry a portion of the purchase price under terms that make the transaction possible.
That is where deal structure becomes strategy.
Price and Terms Are No Longer the Same Conversation
Imagine two offers on the same property.
One buyer offers a lower price with conventional financing and a relatively straightforward closing.
Another buyer is willing to move closer to the seller's asking price but needs the seller to carry a portion of the acquisition.
Which offer is better?
There is no universal answer.
And that is precisely the point.
Commercial real estate transactions increasingly have to be evaluated as complete structures rather than simply competing purchase prices.
The highest price may not produce the strongest transaction.
The largest down payment may not produce the best long-term outcome.
The fastest closing may not always create the greatest value.
Price matters.
But so do interest rate, term, security, liquidity, timing, tax consequences, risk, and the financial objectives of both parties.
The negotiation has become multidimensional.
Alternative Capital Is Filling the Gaps
Banks are also no longer the only meaningful source of capital in many transactions.
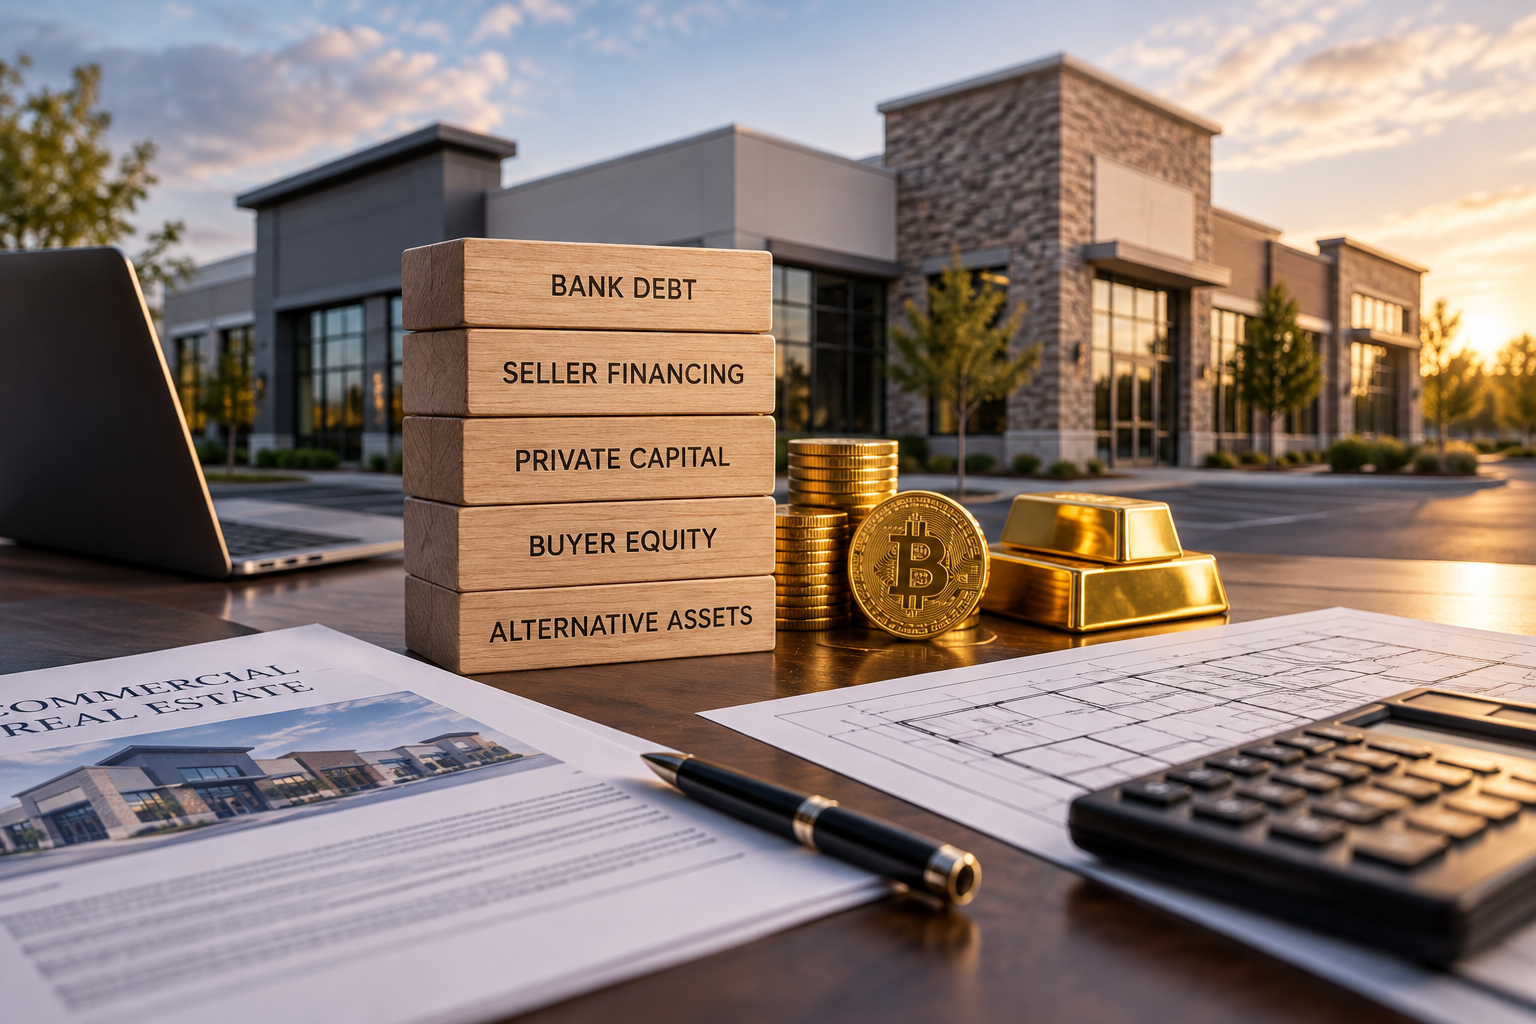
Private lenders, debt funds, family offices, investment partnerships, seller financing, mezzanine capital, and other forms of alternative financing are playing larger roles across commercial real estate.
That creates both opportunity and complexity.
Capital has not disappeared.
It has become more fragmented.
And that distinction matters.
A buyer who receives a disappointing answer from one lender may still have a viable acquisition. The structure simply may not look the way it would have looked several years ago.
The same applies to sellers.
A seller who insists that every buyer arrive with a conventional bank commitment may unnecessarily narrow the field, particularly for properties that require more creativity.
The next generation of transactions may involve several sources of capital working together instead of one lender funding the majority of the acquisition.
That is the new capital stack.
Even the Definition of Consideration Is Expanding
Some of the more interesting conversations happening in today's market involve buyers who have substantial wealth but do not necessarily hold that wealth entirely in cash.
Business interests.
Investment accounts.
Digital assets.
Precious metals.
Other real estate.
A buyer can be financially strong while still preferring not to liquidate an asset simply to satisfy the traditional expectations of a commercial transaction.
That is leading to more conversations about alternative forms of consideration and creative capitalization.
Cryptocurrency and even gold may enter those conversations.
That does not mean either one suddenly replaces conventional financing, nor does using an alternative asset automatically create favorable tax treatment.
In fact, noncash consideration can create additional valuation, documentation, legal, tax, and regulatory considerations.
But the fact that these discussions are taking place tells us something important about the market.
Investors are thinking differently about liquidity.
They are asking whether capital must always be converted into cash before it can become useful in a transaction.
And sophisticated sellers are beginning to consider whether the traditional cash-at-closing model is the only structure worth entertaining.
Liquidity Has Become Part of the Deal
Perhaps the most important change is the renewed value being placed on liquidity.
During periods of inexpensive and readily available credit, investors could maximize leverage and preserve more of their own capital.
Today, the conversation is different.
Lenders want stronger borrowers.
Borrowers want to preserve working capital.
Investors want flexibility.
Sellers want certainty.
Those goals can conflict.
A buyer may have enough money to satisfy a large down payment but be unwilling to leave themselves with little liquidity after closing.
That is not necessarily weakness.
It can be prudent capital management.
Commercial property ownership carries uncertainty. Repairs happen. Tenants leave. Leasing costs arise. Insurance changes. Improvements become necessary. Opportunities appear.
An investor who commits every available dollar to the acquisition may own the building but lose the flexibility needed to operate it strategically.
That reality is beginning to influence how deals are structured.
Creative Does Not Mean Reckless
There is an important distinction between creative financing and irresponsible financing.
Creativity cannot rescue a fundamentally bad deal.
It should not be used to hide insufficient cash flow, excessive pricing, weak sponsorship, or risk that neither party fully understands.
Creative structure works best when the underlying transaction makes sense but conventional financing does not perfectly align with the objectives of the buyer and seller.
That distinction matters.
The goal is not simply to find another way to get the deal closed.
The goal is to create a structure that both sides can live with after the closing.
Because the closing table is not the end of the transaction.
It is the beginning of the ownership period.
This Changes the Role of the Broker
This financing environment also changes what sophisticated commercial brokerage looks like.
Finding the property is only one part of the assignment.
Understanding what may prevent the transaction from closing is becoming equally important.
That may require recognizing early that conventional leverage is unlikely to support the purchase price.
It may mean identifying when seller financing deserves discussion.
It may mean understanding that a buyer is financially capable but liquidity-conscious.
It may mean bringing lenders, attorneys, accountants, and other advisors into the conversation earlier.
And sometimes it means recognizing that a deal that initially appears too far apart may actually have room to come together once price and terms are considered separately.
The broker does not replace the lender, attorney, CPA, or financial advisor.
But the commercial broker is often positioned in the middle of all of those conversations.
That position matters.
Because increasingly, the question is no longer simply whether a deal exists.
It is whether the deal can be structured.
The New Negotiation
The next phase of commercial real estate may demand more creativity from everyone involved.
Buyers may need to bring more equity.
Lenders may continue to demand stronger liquidity.
Sellers may have to consider whether terms are as important as price.
Investors may look beyond traditional banks for portions of their capital stack.
And some transactions may involve structures that would have received little consideration when inexpensive financing was readily available.
None of this means traditional financing is disappearing.
It means traditional financing may no longer solve every transaction.
And that may fundamentally change the way commercial real estate deals are negotiated.
The most interesting opportunities may not come from finding the seller willing to accept the lowest price.
They may come from finding the structure where the interests of the buyer, seller, and capital provider actually align.
The Bottom Line
Commercial real estate has always required capital.
What is changing is the way that capital comes together.
Interest rates matter.
Bank lending matters.
Liquidity matters.
But increasingly, structure matters just as much.
The transaction that closes may not be the one with the highest offer, the biggest loan, or the simplest financing.
It may be the one where both sides are willing to think differently about how value is exchanged and how risk is shared.
That is why financing is no longer something that happens after the deal is negotiated.
Financing has become part of the deal itself.
And the next commercial real estate cycle may not belong to the buyer with the most cash or the seller with the lowest price.
It may belong to the parties willing to structure the better deal.